Dear Complaints Team.
I have a detailed complaint below. My suggestion is that you immediately escalate this to a senior complaints manager within the UK Office, since I’m not going to let this one pass easily.
Point 1 – An Error by Three
It has come to my attention that, unfortunately, Three failed to charge my monthly direct debit bill, twice, once in April and May.
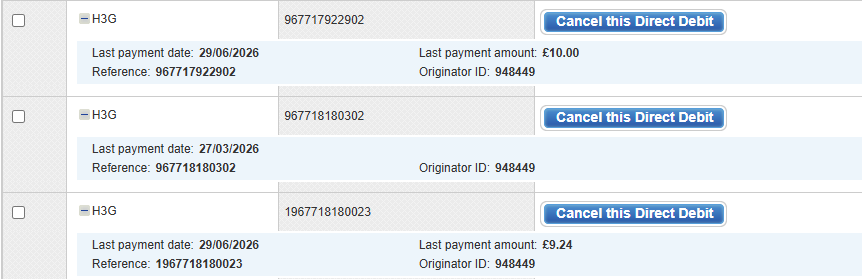
There was no action on my part to cause this. I did not (and have not) cancel any direct debits. There was still a positive balance in the relevant bank account and the direct debit is still active (attached image shows the still active direct debit, second one down).
Around the 25th June, I noticed on my Three Account that there was a larger than normal balance owing, and rang to clarify the cause. (I also discovered I’d been mistakenly charged for a international calling bundle for several months at that time, which was refunded).
The normal monthly payment was then taken on the 29th June without issue. My details didn’t change, I didn’t sign a new agreement; I was not informed that I had made any mistake or failing. The failure for the payments in April and May was entirely a failing within Three’s procedures or actions.
Indeed, on my third complaint call on the 29th July, the advisor confirmed that his records showed the direct debit was unilaterally cancelled by Three on 1st April, and that his records showed no request, failure or action on my part, and no contact between Three and myself on that day.
Action 1: Please investigate the error, and confirm fault on your part, then confirm in writing to me that the error was on Three’s part, not my own.
Point 2 – Error placed on my credit record
Unfortunately, Three registered YOUR failure to collect a direct debit as two “non payment” actions on MY credit record.
This has damaged my credit score, to the degree that my previously approved mortgage has been cancelled. I, a doctor earning above the 40% tax threshold with no debts and no outstanding loans, have a worse credit rating than my wife who earns underneath the personal allowance.
In fact, I am unable to get a mortgage through the provider I was using, and have had to pay a financial advisor to get a wider-market mortgage, at an additional fee cost of £595.
Point 3 – An adequate letter from Three
I complained to Three and escalated my complaint on the 20th July, and was promised a letter, containing the following:
a) Confirmation that Chris Lowry has done nothing wrong to lead to non payment of bills.
b) Confirmation that the error was entirely on Three’s part.
c) Confirmation that Three have made two incorrect entries on my credit score (with details of the entries), and confirming that Three have applied to have them both removed.
On the 22nd I received a complaint letter. It did not clarify that I had not been at fault, nor acknowledge that Three are to blame, or confirmed specifically that the offending two entries have been removed. It was also written in poor English and didn’t use tenses correctly, as you can see:
“Please note, this account is still active and credit file would get updated via the monthly tape.
All negative entries removed from your credit file”.
I need Three to acknowledge fault as I need evidence I can take to mortgage providers that demonstrates I have not acted in a way that would discourage lending. Not just a mention of negative entries, but confirmation that I am trustworthy for lending, and have not demonstrated negative behaviours.
I immediately requested a better letter on the 25th. This complaint was closed without a new letter or any reply to me.
Action 2: I need a letter clearly confirming points a, b and c above.
Point 4 – Repeated complaints not resolved
I was very clear about the letter I needed (including a, b and c) in my complaint on the 20th July.
I was very clear about the letter not being good enough in my complaint on the 25th.
I was very clear about my needs in the online chat and telephone call on the 29th, but have still had to write this letter because it was clear my concerns had not been heard..
Three’s actions have also derailed my house purchase significantly, already having added two weeks (so far), to a process we were hoping would be eight weeks. The issue is absolutely not resolved yet, so that delay will continue.
Action 3: I want an apology. I also expect goodwill compensation for the extremely poor service. I suggest £100.
Point 5 – Other Financial Costs arising from Three’s Negligence
Due to Three’s negligence in managing my financial records responsibly, my credit rating has been seriously harmed. I do not have the luxury to wait 3 months for this to partially reverse, since I will lose the purchase of my house with that delay. Even then, some mortgage providers have made it clear they will not consider me for a further year after a failed credit check. I have been forced to hire a financial advisor to help me access outside of the standard mortgage market, as I am not eligible for standard cover due to Three’s actions. Cost: £595
(I am happy to provide record of this cost, as well as confirmation from my prior mortgage sourcer that the cause for them not being able to help me was the error made by Three)
I have had to spend an hour engaging with Three’s complaint department on three occasions, and spend an hour writing this letter. I am a GP, and my standard hourly rate is £90 per hour. Current cost: £360.
Please note: this cost will be increased by each hour I need to spend continuing this complaint.
Action 4: I expect full compensation of £1055 ( £100 + £595 +£360).
If this is not agreed and paid in full by the 29th August , I will seek redress through the small claims court.
In that situation, I will also be adding my court filing costs, and any difference in cost between the 4.29% mortgage I was offered and whichever mortage I end up having to get, over the fixed term of the mortgage. (For example, if I have to get a 3 year 4.7% mortgage, that will be £81 per month more expensive, or £2,916 over three years.
As a reminder, negligence is demonstrated by
- Does a company owe you a duty of care? Yes, you do.
- Has it breached that duty by acting unreasonably? You cancelled my direct debit unilaterally, then recorded it as a failure on my part without actually checking the cause of the missed payments; namely, the cause being actions taken by Three, not myself.
- The breach caused damage to your credit record. Demonstrably.
- You suffered a measurable loss (for example, being refused credit, paying higher interest, or financial loss). As evidenced above.
Please provide a prompt response and clearly numbered reply to the numbered Action Points. I suspect the best option would be a call (number ends in 891) to acknowledge receipt, and then an extremely comprehensive and clear email.
Yours sincerely,
Dr Chris Lowry